Self-Employed? Qualify for a Home Loan Using Your Bank Statements.
Tax returns don't always show what business owners really earn. A bank statement loan uses 12 to 24 months of personal or business deposits to document your income, so your write-offs don't hold you back.
Luna Lending is an independent mortgage broker with access to multiple non-QM lenders. We compare programs and match you with the one that fits how you actually earn.
Thanks, we've got it.
Aaron will reach out shortly to talk through your income and options. Want to skip the phone tag? Pick a time that works for you.
Book a free consultation Or call (530) 314-9544Built for people who are their own boss.
If your tax returns understate your income because of business write-offs, a bank statement loan can show lenders the full picture.
Business owners
LLC, S-corp and sole proprietors who reinvest in the business and take legitimate deductions that lower taxable income.
1099 contractors and freelancers
Consultants, tradespeople, creatives and independent professionals paid on a 1099 instead of a W-2.
Commission and seasonal earners
Real estate agents, salespeople and seasonal business owners whose income varies month to month.
Buyers turned down by a bank
If a bank said your tax returns don't qualify, a non-QM program may look at your income differently.
Your deposits tell the story your tax returns don't.
Instead of relying on tax returns, most bank statement programs review your recent deposits to calculate qualifying income. We'll walk you through exactly what's needed for the program that fits you best.
- Typically 12 or 24 months of personal or business bank statements (some programs accept fewer)
- Proof of self-employment, typically about 2 years (business license, CPA letter or similar)
- Credit, asset and reserve documentation, which varies by program
- Options for primary homes, second homes and investment properties
Most banks don't offer these loans. We shop them for you.
Typical bank
- Usually requires 2 years of tax returns
- One set of in-house loan products
- Self-employed income often reduced by write-offs
- Little flexibility outside standard guidelines
Luna Lending
- Bank statement, P&L, 1099 and asset-based options
- Programs from multiple non-QM lenders, compared side by side
- 21 years of experience structuring self-employed loans
- One local broker from first call to closing
Business owners, in their own words.
Reviews from Luna Lending's Google Business Profile, shortened for length. Individual experiences vary.
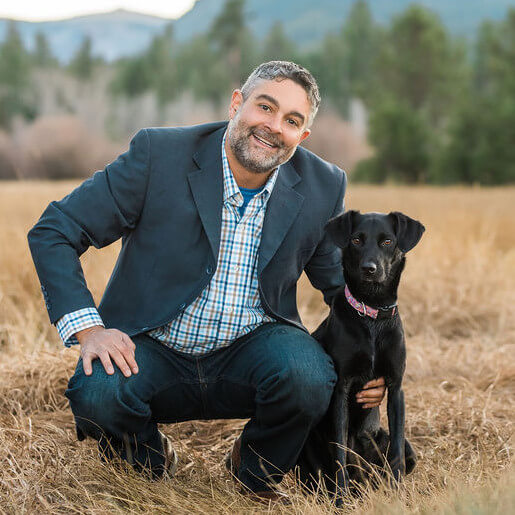
Hi, I'm Aaron. I've helped self-employed buyers for 21 years.
I know how frustrating it is to run a successful business and still hear "your tax returns don't qualify." I started Luna Lending to give self-employed buyers honest advice, clear communication and access to loan programs most banks don't offer.
We're based in Lake Tahoe and work with clients across Northern California. Most of the process happens securely online and by phone, and you'll work directly with me from first call to closing.
Bank statement loans, explained.
What is a bank statement loan?
It's a type of non-QM (non-qualified mortgage) loan that documents your income using personal or business bank statements instead of tax returns. It's designed for self-employed borrowers whose tax returns don't reflect their true earning power.
Do I need to provide tax returns?
Most bank statement programs don't require personal or business tax returns to calculate income. Exact documentation varies by lender and program, and we'll tell you up front what yours requires.
Personal or business bank statements?
Many programs accept either. Business statements typically use an expense factor or a P&L to calculate income. We'll help you figure out which approach works best for your situation.
How do these loans compare to conventional loans?
Because they use alternative documentation, non-QM loans often have higher rates and may require a larger down payment or more reserves than conventional loans. We'll show you real options side by side so you can decide what makes sense.
Can I use one for a second home or investment property?
Yes. Bank statement programs are available for primary homes, second homes and investment properties, subject to each lender's guidelines.
Your business works hard. Your home loan should work with it.
Find out if a bank statement loan fits. A quick conversation with a broker who specializes in self-employed buyers.